What is usually covered
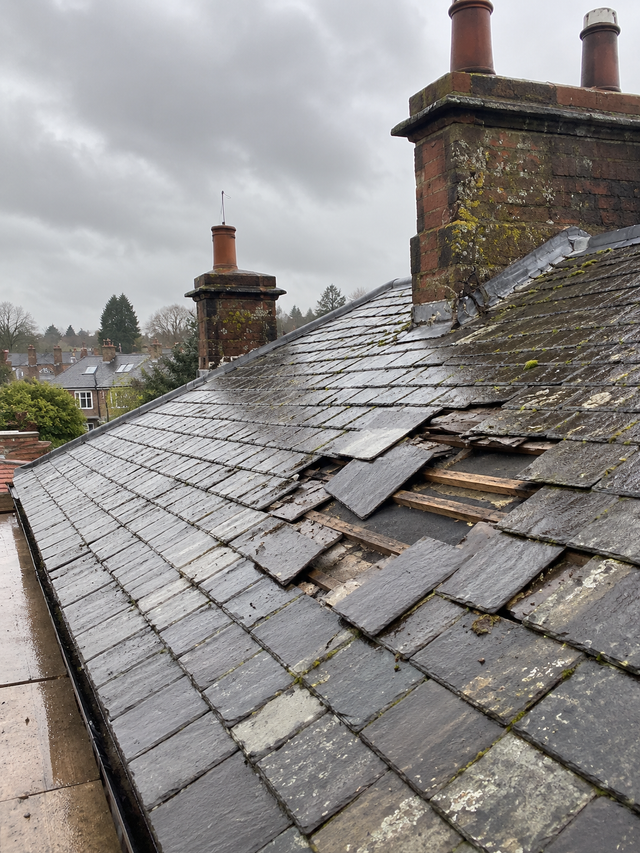
Buildings insurance generally covers sudden, unexpected damage. For roofs that most often means storm damage, falling trees or branches, and fire. Damage inside the house caused by the leak may also be covered.
What is usually not covered
Insurers generally exclude wear and tear and lack of maintenance. If tiles slipped because the fixings had corroded with age, or a flat roof leaked because it was worn out, a claim is likely to be declined even if it happened during bad weather.
Storm damage claims
Insurers have their own definition of a storm and may check weather records for your area on the date of the damage. They may also send a surveyor or loss adjuster to assess whether the roof was in reasonable condition beforehand.
Evidence that helps
- Dated photos of the damage, outside and inside
- Photos of any debris on the ground
- A written report and quote from a roofer
- Records of previous maintenance or repairs
Emergency repairs
Policies generally expect you to take reasonable steps to prevent further damage, such as a temporary repair or cover. Keep the receipts, and tell your insurer before permanent work starts so they can approve it.
How a roofer can help
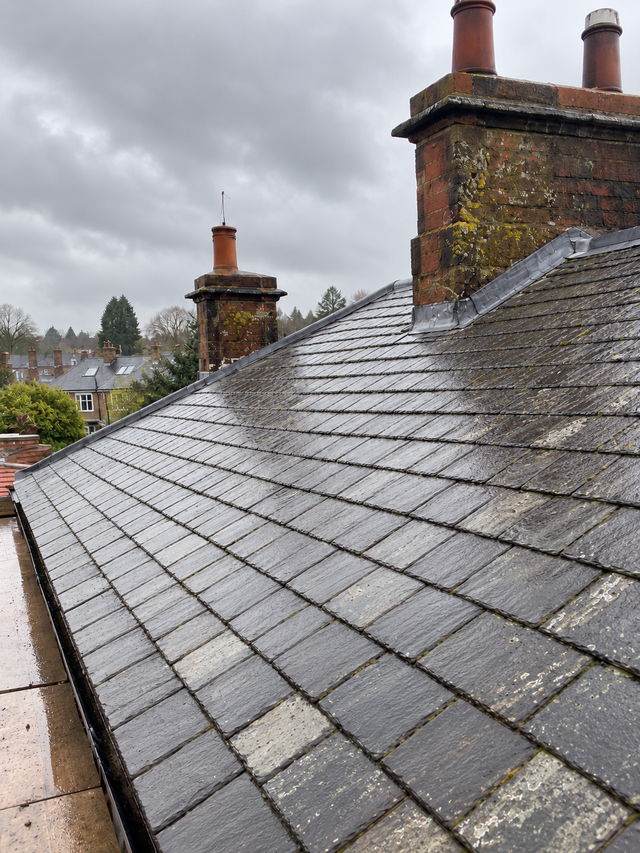
We provide photos of the damage and a written description of the cause and the repair, which you can pass to your insurer. The decision on any claim rests with them.